Are Corporate Gifts Tax Deductible? UK Rules for Client and Staff Gifts
Are corporate gifts tax deductible in the UK? A plain-English summary of HMRC's rules on client gifts, staff gifts, trivial benefits and VAT, with gov.uk links.
By Zintora Team
Are corporate gifts tax deductible in the UK? Client gifts generally are not, unless the gift carries a conspicuous advert for your business, is not food, drink, tobacco or a voucher, and costs no more than £50 per recipient in the period. Staff gifts follow different rules, and small ones may be trivial benefits. Always confirm with your accountant.
General information, not tax advice. Check with your accountant.
This guide sets out, in plain English, how HMRC's published guidance treats gifts to clients and gifts to staff, how VAT works on business gifts and what that means when you choose and brief a branded gift. It links to the official gov.uk pages for every rule, and it uses real Zintora products to show how the rules work in practice. We are a branded merchandise supplier, not tax advisers, so treat this as a starting point for a conversation with your accountant.
Corporate gifts tax deductible: the short version
| Gift | Corporation Tax or Income Tax deduction | VAT on the gift | Tax for the recipient |
|---|---|---|---|
| Client gift with a conspicuous logo, not food, drink, tobacco or a voucher, £50 or less per person in the period | Can be allowable under the gifts exception | No output VAT if gifts to that person cost £50 or less (excluding VAT) in 12 months | Not an employment matter |
| Client gift that fails any of those conditions | Generally not allowable | Output VAT may be due above £50 per person in 12 months | Not an employment matter |
| Staff gift that meets the trivial benefits conditions | Deductible under the employee exception, unless incidental to gifts to others | Ask your accountant | No tax or National Insurance, nothing to report |
| Staff gift that is not a trivial benefit | Deductible under the employee exception, unless incidental to gifts to others | Ask your accountant | Taxable benefit, reported or covered by a PAYE Settlement Agreement |
Each row is explained below, with the HMRC page it comes from.
Gifts to clients: the business entertainment rule
HMRC treats gifts to people outside the business, such as clients, prospects and partners, alongside business entertainment. The starting point is that the cost is not deductible when you work out taxable profits. There is an exception for gifts, set out in HMRC's Business Income Manual on business gifts. In summary, a gift can fall within the exception only if all of these apply:
- it incorporates a conspicuous advertisement for the business;
- it is not food, drink, tobacco or a token or voucher exchangeable for goods;
- the total cost of gifts made to the same person in the period does not exceed £50.
This is why branded merchandise is often discussed in the context of client gifts. A notebook, a pen or a bottle with your logo clearly on it is the kind of item the exception has in mind. A bottle of wine or a box of chocolates is not, however it is presented. Almost everything Zintora supplies is a non-food item that can carry your brand; our one food item, the Toast Snack Box, would fall outside the exception.
What counts as a conspicuous advertisement?
HMRC's guidance refers to a conspicuous advertisement for the business; it does not specify a logo size. In practice, this is a judgement for you and your accountant. A clearly visible logo on the item itself is easier to defend than a mark hidden on the packaging. If you want a discreet look for design reasons, bear in mind that it may weaken the case for the exception.
How the £50 limit works
The £50 limit is per recipient and covers the total of gifts to that person in the period, not each gift. Two £30 gifts to the same client in one year go over the limit. The cost is what the gift costs your business, so ask your accountant how to treat branding, packaging and delivery. Keep a simple record of who received what and when.
Client gift examples from the catalogue
The table lists client gifts from our live product and pack pages. Catalogue prices are ex VAT; printing and delivery are extra, UK import VAT and duties are paid on delivery. For any tax test, use the total in the quote: it separates product, personalisation, packaging and delivery, so you can check the cost per recipient against the £50 limit with your accountant.
| Gift | Minimum | How the logo is applied |
|---|---|---|
| Arc Metal Pen | 50 | Logo can be laser engraved |
| Classic Notebook | 25 | Logo printed or engraved on the cover |
| Atlas Steel Bottle | 25 | Logo laser engraved |
| Ledger Hardcover Journal | 25 | Foil stamping on the cover |
| Relay Power Bank | 25 | Logo laser engraved |
| Orbit Keyboard | 10 | Custom keycap options |
| Executive Client Gift Box | 10 | Confirmed in the quote |
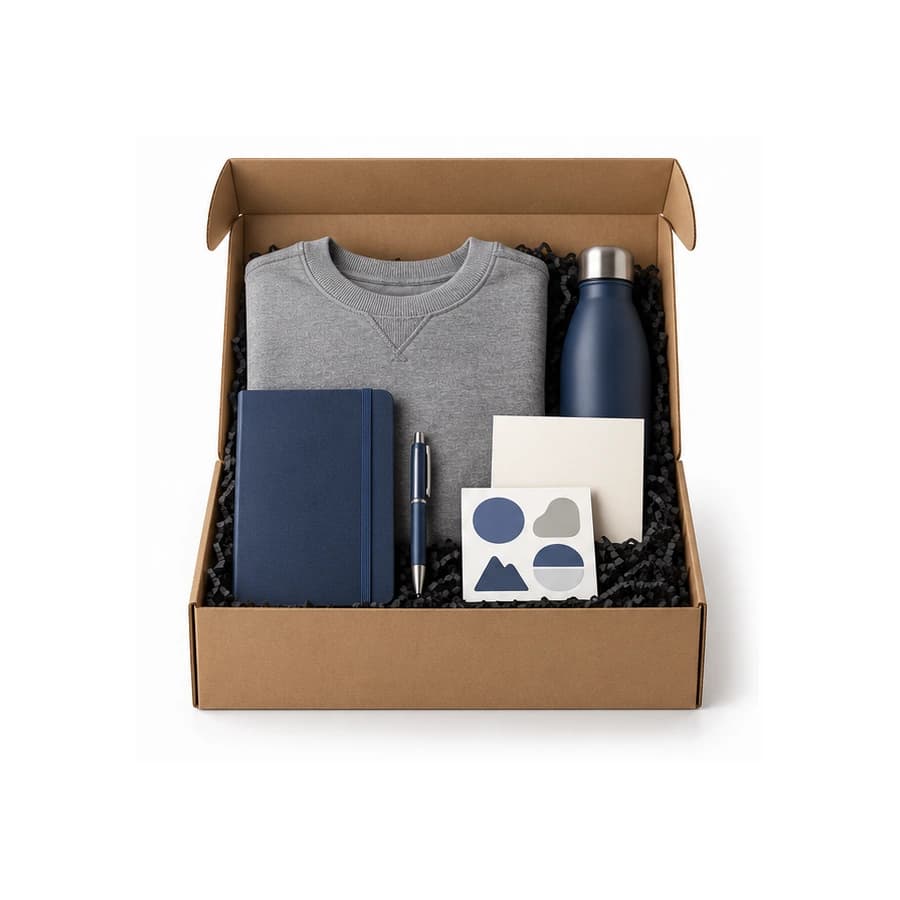
The pattern to watch: once branding, packaging and delivery are added, a single branded item and a premium box for a key client can fall on different sides of the £50 limit, so check the quoted total per recipient. That does not make a premium box wrong; it just means you should not assume a deduction for it. For more client gift ideas, see our corporate gifts page and our guide to corporate gift boxes.
Gifts to employees: trivial benefits
Gifts to your own staff are not client gifts. HMRC's business gifts guidance lists gifts provided to the trader's own employees as an exception to the general rule, so long as they are not incidental to gifts provided to others, which means the cost is generally deductible for the business. For the employee, the main question is whether the gift is a taxable benefit. HMRC's trivial benefits rules say you do not pay tax or National Insurance on a benefit, and do not need to report it, if all of these apply:
- it cost you £50 or less to provide;
- it is not cash or a cash voucher;
- it is not a reward for the employee's work or performance;
- it is not in the terms of the employee's contract.
Directors of close companies (limited companies run by five or fewer shareholders) can receive trivial benefits up to £300 in total in a tax year.
In practice, a Christmas gift or a welcome pack given to all staff can fit these conditions if it stays within the cost limit. A gift for hitting a target, closing a deal or finishing a project is a reward for work, so it does not qualify even if it costs less than £50. Our guide to corporate gifts for employees covers staff gift ideas by occasion and budget.
When a staff gift is not trivial
A staff gift that fails any condition is treated as a taxable benefit under the usual rules: it is reported to HMRC, either through payroll or on the end-of-year form, and the employee pays tax on its value. Some employers prefer to pay the tax on behalf of staff through a PAYE Settlement Agreement, which HMRC explains on its page about PAYE Settlement Agreements. Which route suits you is a question for your accountant or payroll provider.
VAT on business gifts
VAT works separately from Corporation Tax and Income Tax. HMRC's guidance on business promotions (VAT Notice 700/7) covers business gifts. In summary, if you give business gifts to the same person and their total cost is £50 or less (excluding VAT) in a 12-month period, you do not account for output VAT on them. If the total goes over £50 and you were entitled to reclaim the VAT on the purchase, you must normally account for output VAT on the total cost of all the gifts. The notice also explains when you can reclaim input VAT on goods bought as gifts. The details are in the notice itself; ask your accountant how they apply to your business.
What this means when you order branded gifts
None of this should drive the choice of gift on its own: a gift that nobody uses is a poor gift whatever its tax treatment. But a few practical habits help:
- Keep the logo visible on client gifts if you want to rely on the gifts exception, and agree the placement with your accountant.
- Choose non-food items for client gifts, which keeps you away from the food and drink exclusion.
- Budget per recipient, not per item, and keep a record of all gifts to each person in the period.
- Separate staff and client gifts in your records, because different rules apply.
- Avoid tying staff gifts to performance if you want them to qualify as trivial benefits.
- Ask for an itemised quote. Our quotes separate product, personalisation, packaging and delivery, which makes the cost per recipient easier to document.
Packaging options are a printed kraft box or a rigid gift box, confirmed in the quote. For seasonal gifts, our Christmas corporate gifts page lists the current Christmas range with order-by dates.
Timing and delivery
Our general lead time is 10 to 20 working days after proof approval, confirmed in the quote. We deliver across the UK and internationally to Europe, the Middle East and Africa, Asia-Pacific and the Americas. Gifts to recipients outside the UK may raise different tax and customs questions in their country, so check those separately.
If you also report on purchasing, ask with the quote for an estimated carbon footprint per product, sustainability reports with Scope 3 data and certificates for certified products on request. The only certificate supplier we name is GRS of The Tenth House, checked per lot, and we do not buy carbon credits.
Corporate gifts tax checklist
- Gifts split into client gifts and staff gifts
- Client gifts: logo visible, non-food, total per recipient checked against £50
- Staff gifts: trivial benefits conditions checked, including "not a reward for work"
- Close company directors: annual £300 trivial benefits cap considered
- VAT position on business gifts agreed with your accountant
- Itemised quote kept: product, branding, packaging and delivery
- Record kept of each recipient, gift, date and cost
- Accountant has confirmed the treatment before you rely on it
Frequently asked questions
Are client gifts tax deductible in the UK?
Generally not. The exception covers gifts that carry a conspicuous advertisement for your business, are not food, drink, tobacco or vouchers, and cost no more than £50 per recipient in the period. Check with your accountant.
Are gifts to employees taxable?
Not if they meet all the trivial benefits conditions: £50 or less, not cash or a cash voucher, not a reward for work and not contractual. Otherwise they are usually a taxable benefit.
Does a branded pen or notebook count as advertising?
It can, if the logo is a conspicuous advertisement for your business. Check the quoted total per recipient, including branding and delivery, against the £50 limit, and ask your accountant to confirm the treatment.
Can I give food or drink to clients and claim the cost?
HMRC's gifts exception excludes food, drink and tobacco, so the cost is generally not allowable. Zintora supplies non-food branded gifts only.
Do you give tax advice?
No. This guide summarises HMRC's published guidance as general information. General information, not tax advice. Check with your accountant.
Planning client or staff gifts? Browse the catalogue or request a quote with the recipients, budget per person and date. A specialist replies to every request with an itemised quote.